

Vol. 1, No. 2 - August 2026
New Venture Research tracked the EMS industry for more than 30 years, and its flagship research has long been regarded as one of the most comprehensive resources on the market. Now, as part of the Global Electronics Association, the Industry Intelligence team and MMI contributors are happy to continue bringing this valuable intelligence tool to you.
Please note that the first two issues of the new MMI have been offered at no charge. Please subscribe to ensure you receive all future issues.
U.S.-traded Group Sales Estimated to Rise Nearly 30% in Q3 26
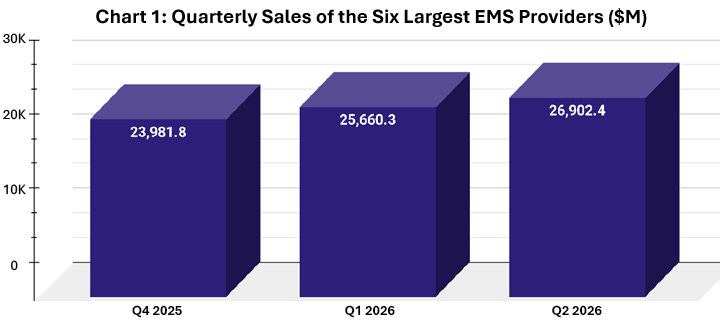
Based on the Global Electronics Association’s estimates for the first nine months, the six largest U.S.-traded EMS providers (Jabil, Flex, Celestica, Sanmina, Plexus, Benchmark) are positioned to deliver robust revenue growth in 2026. Combined sales for the group are estimated to reach $81.24 billion through the first three quarters, representing a 30.1% increase over the $62.45 billion recorded during the same period in 2025.
The Association projects third-quarter sales of $28.68 billion by setting each provider’s revenue estimate equal to the midpoint of its respective guidance range. At that level, group sales would increase 6.6% sequentially from the $26.90 billion reported for the second quarter.
Five of the six providers are expected to achieve sequential revenue growth. Celestica is forecast to post the largest percentage increase, with sales rising 14.9% from the second quarter. Jabil follows with an estimated growth of 9.7%, while Plexus, Benchmark, and Flex are projected to grow by 3.8%, 2.5%, and 2.2%, respectively. Sanmina is the only provider expected to experience a sequential decline, although its projected decrease is limited to 0.4%.
The group’s estimated sequential revenue increase of approximately $1.78 billion is concentrated primarily at Jabil and Celestica. Together, the two companies account for about 87% of the projected dollar increase from the second quarter.
The year-over-year comparison is even stronger. Third-quarter sales for the group are forecast to rise 29.9% from the $22.09 billion generated in the third quarter of 2025. All six providers are expected to report double-digit growth against the year-earlier period.
Celestica is projected to achieve the highest third-quarter growth rate at 69.1%, followed by Sanmina at 64.6%. Plexus is expected to grow 28.0%, while Flex, Jabil, and Benchmark are forecast to post increases of 19.0%, 16.3%, and 13.9%, respectively.
Celestica is also expected to produce the largest year-over-year dollar increase, adding approximately $2.21 billion in third-quarter revenue. Celestica and Sanmina together account for about 54% of the group’s projected $6.59 billion year-over-year increase. Thus, while growth is expected across the entire group, a substantial portion of the expansion remains concentrated among the two fastest-growing providers.
For the first nine months of 2026, every provider is estimated to achieve double-digit revenue growth. Sanmina leads the group with a projected increase of 78.5%, followed by Celestica at 61.9%. Plexus is expected to grow by 25.1%, Flex by 18.9%, Jabil by 16.8%, and Benchmark by 13.0% (see Table 1).
Adjusted EPS guidance also points to generally favorable sequential earnings momentum. Based on the midpoint of each company’s guidance, adjusted EPS is expected to increase at five of the six providers. Jabil is projected to record the largest sequential improvement at 26.6%, followed by Celestica at 17.3%, Plexus at 9.9%, Benchmark at 5.3%, and Flex at 3.5%. Sanmina’s adjusted EPS is expected to decline 3.3% from the second quarter.
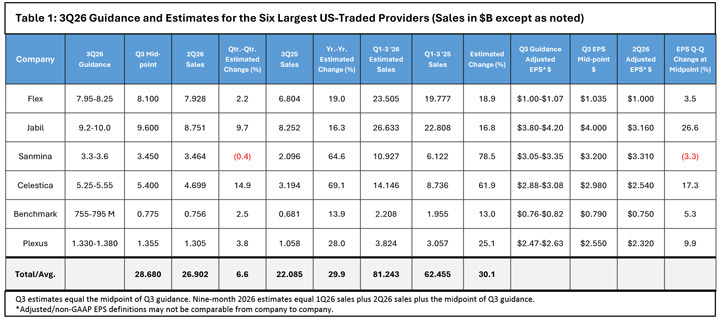
Because adjusted EPS definitions differ among providers, individual EPS amounts should not be compared directly across companies. Nevertheless, the guidance direction indicates that projected revenue expansion is expected to be accompanied by improved adjusted earnings by most groups.
Overall, the guidance summarized in Table 1 presents a strong outlook for the U.S.-traded group. Growth is expected to be both broad-based and substantial, although Celestica and Sanmina remain the principal drivers of the group’s year-over-year expansion.
U.S.-Traded Group Posts Strong Q2 26 Results
The six largest U.S.-traded EMS providers delivered strong revenue growth in the second quarter of 2026. Combined sales for the group reached $26.90 billion, an increase of 4.8% from the $25.66 billion generated in the first quarter and 28.1% above the $21.00 billion reported in the year-earlier period.
Five of the six providers achieved sequential sales growth. Celestica recorded the largest increase, with revenue rising 16.1% from the first quarter. Plexus and Benchmark followed with gains of 12.1% and 11.6%, respectively. Flex increased its quarterly sales by 6.0%, while Jabil posted growth of 5.7%. Sanmina was the only provider to experience a sequential decline, with revenue falling 13.7% from the unusually high level reported in the first quarter.
Celestica was also the largest contributor to the group’s sequential dollar growth, adding approximately $652 million in revenue. Jabil and Flex contributed increases of $469 million and $451 million, respectively. These gains more than offset Sanmina’s sequential decline of approximately $549 million.
When the second-quarter results are compared year over year, an even stronger picture emerges. All six providers achieved double-digit sales growth from the second quarter of 2025. Sanmina posted the highest percentage increase at 69.7%, followed closely by Celestica at 62.4%. Plexus grew 28.1%, Flex 20.6%, Benchmark 17.7%, and Jabil 11.8%.
The group generated approximately $5.90 billion more revenue than it did in the year-earlier quarter. Celestica and Sanmina together accounted for approximately $3.23 billion, or nearly 55%, of that increase. Thus, the expansion was broad-based across the six providers, although the largest portion of the group’s dollar growth remained concentrated at two companies.
For the first six months of 2026, combined sales totaled $52.56 billion, up 30.2% from $40.37 billion during the corresponding period in 2025. Every provider achieved double-digit first-half growth.
Sanmina led the six-month comparison with an increase of 85.7%, while Celestica’s revenue rose 57.8%. Plexus posted growth of 23.5%, followed by Flex at 18.7%, Jabil at 17.0%, and Benchmark at 12.5% (see Table 2). Celestica and Sanmina together produced approximately 55% of the group’s $12.19 billion first-half revenue increase.
Profitability also improved at the group level. The combined second-quarter gross margin was 9.9%, compared with 9.4% in the first quarter and 9.3% in the year-earlier period. This represents an improvement of approximately 50 basis points sequentially and 60 basis points year over year.
Jabil, Sanmina, and Celestica expanded their gross margins from the first quarter. Sanmina reported the largest sequential improvement, with its gross margin rising approximately 170 basis points to 10.4%. Celestica’s gross margin increased approximately 150 basis points to 12.3%, the highest result among the six providers. Flex, Benchmark, and Plexus experienced sequential gross-margin declines.
The group’s combined operating margin reached 6.1%, up from 5.5% in the preceding quarter and 5.6% in the second quarter of 2025. Celestica produced the highest operating margin at 9.8%, followed by Sanmina at 7.0%. Celestica’s operating margin expanded by approximately 310 basis points sequentially, while Sanmina achieved an improvement of about 130 basis points.
Jabil also improved its operating margin from the first quarter. In contrast, Flex, Benchmark, and Plexus reported sequential operating-margin declines, demonstrating that the group’s aggregate profitability improvement was not evenly distributed.
Combined second-quarter net income totaled $1.12 billion, increasing 32.2% from $845.0 million in the first quarter and 50.1% from $744.0 million a year earlier. Five of the six providers increased net income sequentially, with Plexus the only company to report a decline.
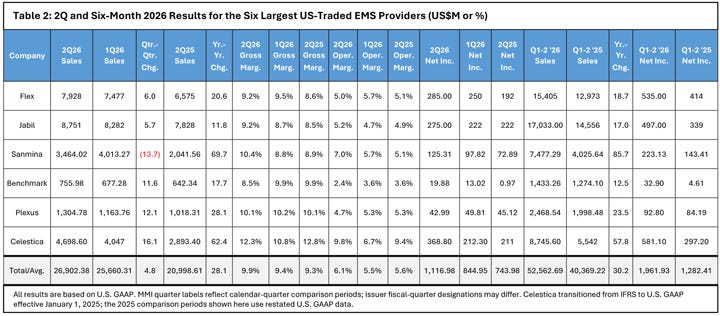
For the first six months, group net income reached $1.96 billion, up 53.0% from $1.28 billion in the year-earlier period. Net income, therefore, grew substantially faster than the group’s 30.2% increase in first-half sales, reflecting the improvement in aggregate operating profitability.
Overall, the second-quarter results show strong and broad-based expansion for the U.S.-traded EMS group. Every provider achieved year-over-year revenue growth, combined margins improved, and net income increased faster than sales. However, the outsized contributions from Celestica and Sanmina and the mixed company-level margin results show that the strength of the group’s performance remained unevenly distributed.
On the conference call, management emphasized that the quarter reflected a more normalized shipment cadence following the unusually strong Q2, which had benefited from accelerated deliveries tied to AI infrastructure programs. Despite the sequential moderation, executives highlighted that underlying demand trends remained strong, particularly in AI server and high-performance computing (HPC) platforms, where customer engagement is expanding across multiple hyperscale and enterprise accounts.
Profitability improved meaningfully during the quarter, with non-GAAP operating margin expanding to 8.0%, compared with 6.4% in the prior quarter and 5.7% a year earlier. Management attributed the margin expansion to a combination of favorable product mix, improved utilization across manufacturing sites, and early synergy capture from the ZT Systems integration, particularly in higher-value server and rack-scale system builds.
Executives reiterated that ZT Systems is increasingly contributing to Sanmina’s exposure to AI infrastructure programs, including rack-scale deployments and liquid-cooled server architectures, which carry structurally higher margin profiles than legacy EMS programs. Integration efforts are progressing ahead of internal expectations, with early procurement and accelerated-compute infrastructure.
A key theme from the conference call was the continued acceleration in AI-related demand, which management described as the primary structural growth driver for the business. Sanmina highlighted that customer engagements in AI infrastructure are broadening beyond initial hyperscaler deployments to include enterprise AI clusters, sovereign cloud initiatives, and specialized compute providers.
Executives emphasized that demand visibility has extended further out, with commentary pointing to strong order momentum into fiscal 2027 and 2028, particularly in high density compute and advanced networking systems. The company also noted that it is actively investing in additional capacity to support next-generation AI platforms, including expanded capabilities in liquid cooling, high-speed interconnects, and system-level integration.
The integration of ZT Systems was a central focus of the call, with management describing it as a transformational step in Sanmina’s evolution toward higher-value, system-level solutions. Executives highlighted that ZT brings deep engineering expertise in AI server design and rack-scale integration, which complements Sanmina’s global manufacturing footprint and supply-chain scale. Integration efforts are focused on engineering alignment in AI server and rack architecture design, supply-chain optimization through component supply-chain consolidation, already beginning to yield cost efficiencies.
Quarterly Results
Sanmina (included in MMI 2Q26 comparison) reported fiscal third-quarter 2026 revenue of $3.46 billion, up approximately 70% year over year from $2.04 billion, driven primarily by the inclusion of ZT Systems and continued strength in the core Sanmina business. Revenue came in near the top end of the company’s $3.2 billion to $3.5 billion guidance range, with management noting that demand remained robust across both traditional EMS programs sourcing and vendor consolidation, and manufacturing scale-up leveraging Sanmina’s global footprint to support higher-volume AI deployments. Early synergy realization is already being reflected in improved margins, with additional benefits expected to ramp through fiscal 2027.
Following the strong quarter, Sanmina raised and narrowed its fiscal 2026 outlook, reflecting increased confidence in both demand visibility and execution. The company now expects revenue of $14.0 billion to $14.3 billion, non-GAAP operating margin of 6.85% to 7.25%, and non-GAAP diluted EPS of $11.90 to $12.20. For the fiscal fourth quarter, it expects revenue of $3.3 billion to $3.6 billion and non-GAAP operating margin of 7.5% to 8.0%. Management also reiterated that the business is entering fiscal 2027 with strong backlog visibility and expanding AI-related program commitments.
Overall, Sanmina’s third-quarter results highlight a clear shift toward a higher-margin, AI-exposed manufacturing platform, with ZT Systems acting as a key accelerant. While sequential revenue normalized after a strong Q2, the more important signal was sustained margin expansion, improving earnings power, and extended visibility into multiyear AI infrastructure demand cycles.
Celestica reported exceptionally strong second-quarter 2026 results, with revenue increasing 62% year over year to $4.70 billion, exceeding the high end of its $4.15 billion to $4.45 billion guidance range. Adjusted EPS increased 83% to $2.54, while adjusted operating margin reached a company record 8.2%, up from 7.4% a year earlier. Management attributed the outperformance to stronger customer demand, improved component availability, and operating leverage across both business segments.
The Connectivity and Cloud Solutions (CCS) segment remained the primary growth engine, with revenue rising 84% to $3.81 billion, representing 81% of total company revenue. Communications revenue increased 62%, driven primarily by continued expansion of 800G networking switch programs and resilient 400G demand.
Enterprise revenue surged 167%, supported by the accelerated ramp of an AI/ML compute program with a hyperscaler and stronger storage demand. Hardware Platform Solutions revenue increased 58% to approximately $1.9 billion, reflecting multiple hyperscaler 800G switch ramps. ATS revenue increased 8% to $888 million, while its margin improved 100 basis points to a record 6.3%.
A key highlight of the earnings call was the accelerating momentum in Celestica’s AI infrastructure pipeline, particularly in next-generation networking. Management confirmed that its first 1.6-terabit Ethernet programs with two hyperscaler customers are expected to enter mass production in the third quarter of 2026. Importantly, the company now has 10 active 1.6T programs, signaling broad adoption across multiple customers rather than a single-platform dependency. While 800G remains a strong growth driver today, management emphasized that 1.6T deployments are expected to scale meaningfully in 2027, marking a major step-change in bandwidth requirements for AI clusters. Customer demand for AI/ML compute has strengthened significantly over recent months, with hyperscaler planning horizons extending into 2028 and, in some cases, 2029—providing unusually long visibility for an EMS provider.
Celestica also disclosed important new AI platform opportunities. The company will work with OpenAI and Broadcom on OpenAI’s multi-generation custom accelerator roadmap, with initial custom-rack deliveries expected in 2026 and mass production beginning in 2027. Management characterized the OpenAI opportunity as potentially multibillion-dollar in scale. Celestica is also the design and manufacturing partner for the scale-up networking switch underpinning AMD’s Helios rack-scale AI platform, another opportunity management described as a growing multibillion-dollar pipeline for 2027.
Supply rather than demand is becoming the principal constraint. Management said AI data center infrastructure demand continues to exceed global component supply, particularly for long-lead materials. However, noncancelable customer orders, supply agreements and increasingly detailed multiyear capacity planning are improving visibility. Celestica is investing aggressively to support these programs, maintaining approximately $1 billion in 2026 capital expenditures, with roughly $1.5 billion currently assumed for 2027. Capacity investments are expanding across Thailand, Japan, and the U.S.
Following the quarter, Celestica raised its 2026 revenue outlook from $19 billion to $20.5 billion, representing anticipated growth of 65%, and increased adjusted EPS guidance from $10.15 to $11.30, implying 87% growth. Adjusted operating margin guidance increased to 8.4%, while expected free cash flow rose from $500 million to $600 million. For Q3, Celestica expects revenue of $5.25 billion to $5.55 billion and adjusted EPS of $2.88 to $3.08. More significantly, management now expects 2027 revenue growth to accelerate beyond the 65% projected for 2026, with adjusted EPS growing faster than revenue as margins expand.
For Q3, Celestica expects revenue of $5.25 billion to $5.55 billion and adjusted EPS of $2.88 to $3.08. Looking further ahead, management expects 2027 revenue growth to accelerate beyond the 65% projected for 2026, supported by scaling 1.6T networking programs, expanding AI compute deployments, and new platform wins with OpenAI and AMD. Adjusted EPS is expected to grow faster than revenue as operating leverage, product mix and manufacturing scale continue to improve.
Overall, the second quarter reinforces Celestica’s rapid transformation from a traditional electronics manufacturing provider into a higher-value AI networking, compute, and rack-scale infrastructure partner, with 800G, 1.6T, OpenAI, and AMD programs providing unusually strong multiyear growth visibility.
North American EMS Group Posts Sequential Growth but Remains Below Prior Year
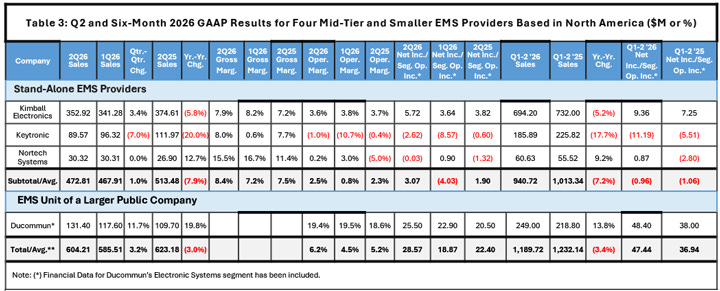
Combined second-quarter sales for four mid-tier and smaller EMS providers based in North America totaled $604.2 million. This represented a 3.2% improvement from $585.5 million in the preceding quarter, but a 3.0% decline from $623.2 million in the year-earlier period. The results suggest that the group achieved sequential stabilization, although year-over-year demand remained uneven. (See Table 3, page 5.)
The three stand-alone providers, Kimball Electronics, Keytronic, and Nortech Systems, generated combined second-quarter sales of $472.8 million. Revenue increased 1.0% sequentially but declined 7.9% year over year. In contrast, Ducommun’s Electronic Systems segment reported sales of $131.4 million, up 11.7% from the prior quarter and 19.8% from a year earlier.
Ducommun accounted for $13.8 million, or nearly three quarters, of the group’s $18.7 million sequential sales increase. This concentration indicates that the group’s improvement was not broad-based.
Kimball Electronics, the largest of the stand-alone providers, reported second-quarter revenue of $352.9 million. Sales increased 3.4% sequentially but declined 5.8% year over year. Kimball’s first-half sales totaled $694.2 million, down 5.2% from the comparable 2025 period.
Keytronic remained the group’s weakest top-line performer. Revenue decreased 7.0% sequentially and 20.0% year over year to $89.6 million. For the first six months, Keytronic’s sales fell 17.7% to $185.9 million.
Nortech Systems generated second-quarter sales of $30.3 million, essentially unchanged from the preceding quarter but up 12.7% year over year. Nortech and Ducommun were the only two providers to achieve year-over-year quarterly growth. Nortech’s first-half revenue increased 9.2% to $60.6 million.
Profitability among the stand-alone providers improved considerably from the prior quarter. Their combined gross margin increased to 8.4% from 7.2% in the first quarter and 7.5% in the year-earlier quarter.
This is consistent with recent history. May’s PCB book-to-bill reached 1.36, and the industry has reportedly stayed above parity for nine consecutive months. That suggests a sustained, if choppy, imbalance favoring demand over supply.
The constraint, as Global Electronics Association Chief Economist Shawn DuBravac notes, is increasingly capacity and lead times rather than order generation. That shifts the industry focus from sales acquisition to execution: labor availability, component access, factory utilization, and expansion timing.
Supporting indicators remain broadly positive. North American PCB shipments rose 12% year over year in June, while bookings jumped 31.5%, signaling continued upstream strength in electronics production. Component sentiment also remains elevated: ECIA’s index hit a five-year high in June before easing in July, though still above its 12-month average.
However, caution is warranted. The Association recently updated its survey methodology, meaning book-to-bill comparisons with earlier periods may not be fully consistent.
For EMS providers, the key question is no longer whether demand exists, but who can convert it into revenue most efficiently. In a capacity-constrained environment, advantage shifts toward firms with available factory space, resilient supply chains, automation, and financial flexibility to expand without margin erosion.
The EMS book-to-bill ratio of 1.33 is therefore less a simple demand signal and more a stress indicator for the manufacturing system.
The message for North American EMS is clear: The market is still expanding, but execution speed is the defining competitive edge.
Economic Update:
AI Pushing Electronics Demand Despite Global Headwinds
By Shawn DuBravac
There are four major economic storylines to watch this month. First, broad macroeconomic conditions continue to soften. Second, the U.S.-Iran conflict has kept energy inflation elevated, delaying disinflation and pushing central bankers toward a more hawkish stance. Third, record-setting global demand for electronics is offsetting headwinds and buoying economic growth. Finally, tight supply-and-demand dynamics in electronics are putting upward pressure on prices and keeping inventories tight.
In the U.S., annualized economic growth slowed to 1.5% in the second quarter, down from 2.1% in Q1. China posted its weakest quarter since 2022, with the economy growing at 4.3% over the last year. In the euro area, Q2 growth was 0.4% quarter-over-quarter and just 1% over the last year, though this is an uptick from Q1 growth.
The biggest headwind remains the persistence of energy-driven inflation and uncertainty stemming from the ongoing U.S.-Iran conflict. In the U.S., consumer energy prices were up nearly 15% year-over-year in July, driven by gas prices that are now 25% higher than they were a year ago. In Europe, energy prices are roughly 10% higher which helped push overall inflation up to 2.9% in July.
Central banks have adopted a more hawkish bias amid inflation, but a lack of unanimity has also helped keep rates steady in many countries. The European Central Bank paused rates at 2.25% after a June hike, but the market fully anticipates a rate hike to 2.5% in September. The Bank of Japan raised its overnight policy-rate to 1% in June but held it there in July. The Bank of England held at 3.75%, but with a 6-3 split decision.
In the U.S., the Fed voted to hold its target rate range at 3.5–3.75% in July. This was the fifth consecutive meeting held at the current level, but there were also three dissenting votes that pushed to raise rates. The financial markets began pricing in a September hike for the U.S., but in the last month a weak jobs report followed by a relatively less aggressive inflation report has the market again betting the Fed holds rates steady for another month.
While inflation and uncertainty weigh on the outlook, the unprecedented AI-driven boom continues to deliver record growth in the electronics sector and remains the key driver of overall economic growth in most regions. Global semiconductor sales were over $400 billion in the second quarter, a 35% increase from the first quarter and a 125% jump over the last year.
In the U.S., the focus has been on both sides of the Fed’s mandate. The labor market lost 23,000 jobs in July and prior months were revised down by just over 100,000 jobs. The three-month average job gain now stands at just 20,000. But labor growth has also slowed which has kept unemployment in check. The unemployment rate fell to 4.1%, aided by a decline in labor force participation. Labor force participation is at the lowest level since February 2021. Wage growth slowed to 3.2%, falling below inflation which means workers are once again losing purchasing power to higher prices.
While overall economic growth slowed in the U.S., equipment investment rose over 15% driven by strength in AI-related hardware. Manufacturing sentiment also remains high. The ISM Manufacturing index rose to 55.6 in July, the highest reading since May 2022. New orders and production were especially strong at 56.7 and 58.5, respectively. The employment index rose above 50 for the first time in 33 months. Although net trade subtracted a full percentage point from overall growth in Q2, final sales to private domestic purchases rose at a much stronger rate. The U.S. domestic economy appears resilient in the face of myriad challenges.
Europe is improving but the recovery is shallow. Europe’s manufacturing PMI rose to 51.9 in July, but industrial production was flat in June, and capital-goods output fell 1.4% in the month. While muted compared to other regions, Europe has also benefited from AI-related demand. Germany’s GDP rose 0.2% in Q2 and July’s manufacturing PMI hit 52.2, matching March’s reading and the best reading since May 2022. Factory orders in Germany rose 3.1% in June, driven by nearly 23% growth in electronics.
China’s economy continues to struggle and consumers remain tepid. The manufacturing PMI fell to 49.2 in July, moving into contractionary territory. New orders dropped to 48.5. Property investment fell 18% in the first half of 2026, household consumption rose just 2.7% and goods retail sales just 1.3%. Despite weaker manufacturing sentiment, exports rose 27% in June. Producer prices are up 3.5% in July, a slowdown from 4.1% in June but far outpacing 0.5% consumer inflation. Upstream cost pressures are outpacing final-demand pricing power.
India’s industrial production was up 7.3% year-over-year in June and July’s manufacturing PMI was 53.5. Merchandise exports reached a record $44.24 billion in July, helped by electronics and engineering products. Electronics imports were up 44% year over year. Most strategically, India approved an additional ₹1.275 trillion, roughly $13.3 billion, for its semiconductor program on July 15. India’s Semicon 2.0 covers six areas: chip design and intellectual property, semiconductor machinery and materials, new fabs, ATMP/OSAT advanced packaging, R&D, and talent development.
Global AI investment is fueling strong exports for many manufacturers. In Korea, July exports hit $98.89 billion, up nearly 63% year-over-year and the second-highest month on record. Semiconductors accounted for $41.01 billion of the total, increasing 178.8%, while computer exports rose 404% to $4.79 billion. In Taiwan, June exports hit a record $95.26, up 59% year-over-year. Electronics exports totaled $40.5 billion, a rise of 80%. Exports to the U.S. were up 84%.
Strong AI-related demand is also keeping inventories tight and prices firm. Lead times have lengthened as demand has built. Demand for high-bandwidth memory, server DRAM, NAND flash, and advanced packaging is outpacing new capacity, while suppliers are reallocating production toward higher-value data-center applications. Memory prices are expected to rise by another 10-20% in Q3, following a 60–70% increase last quarter. U.S. electronics manufacturers report rising input prices, slower supplier deliveries, and declining inventories. Bottlenecks in global electronics supply chains will constrain supply and keep pricing firm.
June North American Book-to-Bill Analysis
By Mike Carano, Executive PCB Advisor, and Mark Wolfe, Executive EMS Advisor
PCB Momentum Stays Hot as Constraints Do the Talking
Editor’s note: The monthly book-to-bill reports summarize shipments and new order activity for North American PCB fabrication and EMS providers based on survey data from participating manufacturers. The book-to-bill ratio is calculated as the value of orders booked over the past three months divided by the value of sales billed during the same period. This narrative is a qualitative companion to the month’s data, synthesized from a discussion between two industry experts focused on what is driving the specific readings and what the numbers do and do not imply.
Sustained strength, not a one-month story
The PCB headline remains straightforward: The market continues to run very busy. The latest data shows shipments growing at a healthy pace year over year, while bookings are growing faster still. That combination keeps the demand signal loud and reinforces that this is not a brief spike driven by a narrow pocket of activity.
Capacity is the limiter, not a lack of orders
What stands out in the discussion is how consistently manufacturers describe the constraint: It is conversion, not demand. Shops are running at high utilization, prioritizing work and, in some cases, quoting longer or declining programs they cannot execute well. The implication for readers is that strong bookings and longer lead times can persist even without any speculative ordering behavior, simply because the system is operating near its practical limits.
“We keep coming back to the same point: This is real demand meeting real capacity. The question is not whether orders exist; it is how quickly they can be converted into shipments.”
— Mike Carano, Executive PCB Advisor
Near-term expansion looks like creativity, not brick and mortar
The capacity response looks tactical. The near-term playbook is overtime, weekend coverage, schedule adjustments, and equipment intensity rather than new facilities. That matters for interpreting the numbers: When the supply base is already stretched, modest incremental demand can translate into disproportionate pressure on lead times and delivery cadence.
Choke points are showing up upstream, not only in the shop
One nuance worth elevating is that constraints are not confined to factory-floor steps. The conversation flagged tightening in specialty materials and process inputs, including areas such as high-performance laminates, specialized copper, and key chemistries. When those inputs are allocated or lead times lengthen, they can shift shipment timing across reporting periods, creating the appearance of a softer month or quarter in a niche even while the broader market remains strong.
Why some specialty segments can look softer without weakening demand
A practical takeaway from our discussion is that a “down” quarter in certain specialty board categories does not automatically mean demand is rolling over. If specific inputs become gating items, build cycles stretch, and shipments move to later periods, which can temporarily depress shipment-based views even as order activity remains healthy. Readers should treat these pockets as supply-chain physics first, not as a definitive demand signal.
Global context matters, even when domestic shops are full
We also noted that capacity is being added in parts of Asia to support compute-intensive demand, including AI infrastructure and related high-layer-count requirements. That does not negate the North American picture, where the immediate reality is constrained conversion. But it is relevant to how readers think about the medium-term balance between supply and demand and where the pressure may ease first.
PCB remains a lagging indicator in the broader electronics cycle
A reminder that holds: PCBs often trail the broader electronics cycle. When upstream electronics spending accelerates, PCB orders frequently follow with a delay as designs stabilize, build scale, and replenishment flows through. Read through that lens, the sustained strength fits a broader narrative of demand that has been building and is now expressing itself more clearly in board orders and factory loading.
Read the full June PCB Book-to-Bill news release here.
EMS Steady, With Bookings as the Signal to Watch
A stable message, with a modest improvement in shipments
On the EMS side, the tone is still one of cautious optimism. Shipments improved month over month, and booking strength remains the more important thread in the current data. The book-to-bill ratio stayed elevated, even with a small month-to-month step down, which keeps the demand signal intact without suggesting a dramatic inflection.
Bookings are stronger than billings, and that gap is informative
A key point from our discussion is that bookings are acting like a leading indicator. The year-over-year lift in new bookings was described as meaningfully positive, while shipments are improving at a more measured pace. That pattern is consistent with a market that is getting healthier but is still working through conversion constraints and normal timing effects rather than snapping into a surge.
“The most useful read right now is that orders are improving, but it is not a flood. It still feels like a steady fill-in and cautious optimism.”
— Mark Wolfe, Executive EMS Advisor
Backlog looks steady, but behavior can create optical noise
Backlog measured in months remains a helpful reference point, but it is also a place where definitions and respondent mix can matter. Our discussion highlighted that larger firms tend to have materially longer backlog coverage than smaller firms, and that booking behavior can create spikes without an immediate matching shift in shipments. For example, customers refreshing blanket orders on a cadence can produce booking bursts that do not indicate a sudden change in end demand.
A category spike is a flag to validate, not a narrative to overfit
One of the most important “inside baseball” items this month is a sharp jump in an “other services” category in the quarterly rollup. Our view was clear: Without more detail, it is hard to narrate responsibly. The most likely explanations include classification differences, one-off respondent behavior, or shifts in the respondent mix. The right action is to tighten definitions and confirm what is driving the change before treating it as a market signal.
EMS is steadier than PCB, and lead-time effects are smaller
Relative to PCBs, EMS tends to look more like a steady-state system in this cycle. Assemblers are not describing the same degree of broad lead-time renegotiation, even though they may be adapting to longer PCB lead times by planning earlier board buys.
A practical reminder for readers is that the EMS ratio can also move mechanically if shipments are delayed by parts constraints: Billings fall, bookings remain, and the ratio ticks up even if demand is unchanged. This month’s movements are not large enough to justify overreading one data point.
Sometimes, the most useful update is what is not happening
There is no sign in the discussion of a destabilizing pattern such as widespread double-ordering or speculative inventory behavior. Supply constraints have not clearly worsened in a step-change way, and demand is not swinging wildly. That steady footing is meaningful in itself, particularly for readers who remember how quickly sentiment can overshoot in either direction.
Read the full June EMS Book-to-Bill news release here.
One Supply Chain, Same Direction
Strong readings, with PCB running hotter and EMS improving steadily
Both segments point in the same direction: Demand is present and improving, but conversion constraints shape how that demand shows up in the data. PCBs remain the hotter side, with capacity and upstream inputs acting as practical limiters. EMS remains steadier, with booking strength offering the clearer forward signal while shipments improve at a measured pace.
What readers should watch over the next few reports
The most important signals are about persistence, not a single month’s swing. For PCBs, watch whether elevated bookings continue and whether constraint-driven lead times and allocations broaden beyond a few specialty inputs. For EMS, watch whether bookings remain firm relative to billings and whether backlog stays stable as conversion improves.
Also, watch the data hygiene items: When a broad catch-all category jumps, the right move is validation and a tighter definition, not story-building.
The bottom line
This month’s message for PCB fabricators and EMS suppliers is not a new twist but a clearer reinforcement of what the market is already showing: true demand meeting practical constraints. If booking strength persists and the constraint indicators remain firm, the implication is you will see continued pressure on delivery performance and prioritization, rather than a drop in demand.
Company Investment News: Mergers, Acquisitions, Expansions
NEOTech Acquires Virtex, Expanding U.S. Defense Manufacturing Footprint
NEOTech is adding significant scale to its U.S. manufacturing network with the acquisition of Virtex, a move that strengthens the company’s position in high-reliability electronics manufacturing for defense and other demanding end markets.
NEOTech, a portfolio company of Arkview Capital, said the combination will create an organization with 11 manufacturing facilities and more than 2,500 employees. Financial terms were not disclosed.
Virtex brings five U.S. facilities and a broad portfolio of electronics manufacturing capabilities spanning engineering and test, printed circuit board assembly, cable and harness manufacturing, system integration, supply chain management, direct-order fulfillment and aftermarket services. For NEOTech, the attraction goes beyond additional factory space.
The deal expands its ability to support customers across a larger portion of the product life cycle, from early-stage engineering and prototyping through volume production, fulfillment and ongoing life-cycle support. It also adds further domestic capacity for complex, low-to-medium-volume, high-mix manufacturing, an increasingly important segment for defense programs where product complexity, traceability and reliability often matter more than pure production scale.
The enlarged ITAR-registered U.S. manufacturing footprint is particularly significant. Defense and aerospace customers continue to place greater emphasis on domestic sourcing, supply chain security and manufacturing resilience, making qualified U.S. capacity an increasingly strategic asset for EMS providers serving mission-critical programs.
Arkview Capital co-founder Pavel Chernyshov said the acquisition is part of the firm’s strategy to build NEOTech into a larger-scale manufacturing partner capable of supporting sophisticated defense products.
The transaction also reflects a broader consolidation theme within the North American EMS market. Rather than pursuing scale purely through higher-volume commercial electronics, providers serving defense and other regulated markets are increasingly building differentiated portfolios around engineering depth, high-reliability manufacturing, secure supply chains and specialized certifications.
NEOTech said investment will continue across the combined organization, including manufacturing technology, engineering resources, quality systems, supply chain capabilities and workforce development.
For customers, the real test will be how effectively NEOTech integrates Virtex’s five plants and converts the larger footprint into greater capacity, broader technical capability and more resilient domestic program support.
If successful, the acquisition gives NEOTech substantially more weight in the competitive U.S. high-reliability EMS market.
Heron Power Selects First U.S. Factory for Next-Generation Power Electronics
Heron Power, an American advanced power electronics manufacturer, announced it has selected Morgan Hill, California as the home of its first large-scale factory. Heron Power will convert a former 286,000 square foot distribution warehouse 30 minutes south of San Jose into an advanced manufacturing facility to produce Heron Link, a 5-megawatt medium voltage power conversion system for large scale energy and datacenter projects.
Heron’s first factory is designed to manufacture up to 10,000 Heron Links a year, over 40 gigawatts annually, roughly three-quarters of the total new generating capacity the entire U.S. grid added in 2025, the largest single-year buildout in over two decades. Heron expects to add more than 600 jobs in advanced manufacturing, engineering, and operations roles in California and invest over $100 million in the facility. Site preparation for manufacturing begins immediately, with mass production slated to begin in late 2027.
Over the past two decades, grid-edge technologies like batteries, solar, electric vehicles and compute have advanced dramatically in capability and affordability. However, the hardware on the other side of the wire has not kept pace with this progress. Much of it is decades-old, largely mechanical technology that is increasingly more expensive, hard to source, and ill-matched to the dynamic, bidirectional, growing demand for end-use electrification, new manufacturing, and AI data-centers. Compounding the problem, over 80% of critical grid components such as transformers and inverters is imported.
“America’s grid has to grow faster than it has in decades. We’re seeing new demand from AI and EVs, and at the same time new supply from solar and storage,” said Drew Baglino, CEO and Founder of Heron Power. “The equipment running the grid hasn’t changed in fifty years. Heron Factory One in Morgan Hill is how we fix that. We’re manufacturing the leapfrog technology our grid needs, at scale, in America first.”
Heron Power evaluated manufacturing locations across multiple states before selecting Morgan Hill. The decision places manufacturing near Heron’s engineering headquarters and the broader Bay Area’s engineering and manufacturing deep talent pool, accelerating Heron Factory One’s ramp to full output, quality, and cost targets. The City of Morgan Hill, PG&E, and state partners worked alongside Heron Power and its real estate advisor JLL over ten months to select the facility, which is supported in part by a $26.4 million California Competes (CalCOMPETES) award, a competitive, merit-based tax credit administered by CA GO-Biz.
RRP Electronics Moves Toward Full-System Manufacturing with Vital Electronics Deal
RRP Electronics is looking to move further down the electronics manufacturing value chain, signing a memorandum of understanding and term sheet to acquire 100% of Vital Electronics, an EMS provider with capabilities spanning PCB assembly through finished system integration.
The proposed transaction represents a significant strategic expansion for RRP, which has primarily been building its presence around outsourced semiconductor assembly and test (OSAT) and assembly, testing, marking and packaging operations.
Under the planned structure, RRP will acquire Vital Electronics in four tranches, targeting 50% ownership by March 2027 and completion of the acquisition by March 2028, subject to agreed milestones and regulatory approvals.
Vital brings a broader manufacturing stack that includes surface-mount technology, printed circuit board assembly, electromechanical assembly, engineering, component sourcing, testing, system integration, packaging and box-build services.
For EMS industry observers, the significance lies in how those capabilities could fit alongside RRP’s semiconductor operations.
Rather than operating only at the chip packaging and testing level, the combined organization could potentially support a more vertically integrated manufacturing chain in which semiconductor devices are packaged, assembled onto PCBs and ultimately incorporated into finished electronic systems.
RRP is targeting applications across defense, automotive, industrial, telecommunications and consumer electronics, giving the company exposure to markets requiring very different combinations of volume, complexity and manufacturing qualification.
If completed successfully, the acquisition would mark RRP’s evolution from a semiconductor-focused manufacturer toward a more comprehensive electronics manufacturing platform spanning chip packaging to finished systems.
Fabrinet Adds Silicon Valley Footprint With $77 Million Campus Purchase
Fabrinet has expanded its U.S. real estate footprint with the $76.9 million all-cash acquisition of a three-building office campus in Santa Clara, California, through a subsidiary.
The Bunker Hill Lane property totals approximately 225,000 square feet and sits near another Fabrinet-owned facility on Patrick Henry Drive.
For the Thailand-based contract manufacturer, the purchase strengthens its physical presence in Silicon Valley, placing additional space close to customers and technology partners in optical communications, advanced electronics and related high-growth markets.
While Fabrinet has not disclosed how the campus will be utilized, the size of the investment makes the transaction noteworthy for EMS industry observers. The additional property could provide flexibility for engineering, customer engagement, administrative functions or future operational expansion. The acquisition adds another strategic U.S. asset to Fabrinet’s predominantly Asia-centered global manufacturing network.
NVIDIA Partners With Major Firms to Mobilize $500B for AI Infrastructure
NVIDIA announced strategic partnerships to establish independent compute financing platforms with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilize over $500 billion of third-party capital for the buildout of AI infrastructure over time.
Demand for AI infrastructure continues to accelerate as countries, governments, enterprises and startups look to drive innovation, economic growth and societal benefits. NVIDIA compute is an investable asset—one which provides the lowest token cost, highest revenue and longest life along with a rich ecosystem of offtakers built upon NVIDIA’s CUDA platform.
Memorandums of understanding signed with six of the world’s premier financial institutions to create these partnerships aim to establish the first compute financing platforms of their kind at global scale to enable the AI infrastructure buildout across NVIDIA’s ecosystem, including leading frontier AI labs, enterprises and AI clouds. Under these strategic partnerships, NVIDIA will work with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to create dedicated pools of capital at significant scale at attractive rates for NVIDIA customers.
“NVIDIA has reached an important milestone. We began by building chips; today, we are helping create a new class of productive, investable infrastructure: AI factories,” said Jensen Huang, founder and CEO of NVIDIA. “In AI, compute is revenue. NVIDIA compute is uniquely suited for this role. It is broadly adopted, flexible across models and workloads, fungible and transferable across customers and operators, and continuously improved through CUDA software—extending its useful life and improving its economics over time. It is supported by a deep global ecosystem of developers, customers and offtakers. That is why we are bringing the world’s leading long-term capital providers together to independently underwrite AI infrastructure. These financing platforms will help customers access scarce compute at scale and build the DSX AI factories that will power every industry and country in the age of AI.”
These partnerships remain subject to execution of the final agreements.
Nvidia Backs Naver’s Korean AI Factory as Sovereign Infrastructure Buildout Accelerates
Nvidia is putting $1 billion into South Korea’s Naver, deepening a partnership that could create one of Asia’s more significant sovereign AI infrastructure platforms and another major source of demand for the electronics manufacturing supply chain.
Under the expanded plan, Naver, Nvidia and Brookfield Asset Management intend to increase the initial Nvidia DSX AI factory deployment at Naver’s GAK Sejong hyperscale data center from 55 MW to 200 MW by 2028. Naver ultimately intends to expand its Nvidia infrastructure deployment to 1 GW.
Nvidia’s investment is expected to give it approximately a 4.5% stake in Naver, while Brookfield has proposed providing up to $9 billion in infrastructure financing. For EMS and electronics hardware suppliers, the important number may be 200 MW rather than $1 billion.
For the EMS sector, the signal is straightforward: AI infrastructure capital spending is spreading from a handful of hyperscalers into national and regional platforms.
Market News
AI Server Shipment Forecast Raised to 31% as Hyperscaler Spending Accelerates
The AI infrastructure buildout is gathering more momentum, with TrendForce raising its 2026 AI server shipment growth forecast to nearly 31% year over year, up from 28% previously.
The revision follows a sharp increase in expected capital spending by the world’s largest cloud service providers. TrendForce estimates that combined 2026 capital expenditures from Google, Amazon, Meta, Microsoft, Oracle, ByteDance, Tencent, Alibaba and Baidu will exceed $886.7 billion, representing roughly 90% year-over-year growth. The five major North American hyperscalers are expected to account for nearly 90% of that total.
For EMS and ODM suppliers, the significance extends well beyond server assembly.
Demand is strengthening for Nvidia GB and VR rack-scale platforms, while Google and AWS are preparing to ramp next-generation in-house ASIC platforms in the second half of 2026. Chinese hyperscalers are also accelerating domestic AI infrastructure programs, with ByteDance, Tencent, Alibaba and Baidu expected to increase combined capital expenditures by more than 80%.
That spending is broadening the manufacturing opportunity across the AI hardware stack. In addition to compute systems, hyperscalers are investing heavily in liquid cooling, advanced packaging, high-speed interconnects, memory, power infrastructure and rack-level integration.
The architecture mix is also becoming more complex. Google continues to expand TPU deployments, AWS is combining Nvidia GB300 systems with internally developed ASICs, while Meta is expected to rely on Nvidia and AMD rack-scale platforms before increasing deployment of its own AI silicon in 2027. For EMS companies, this creates both opportunity and operational pressure. Winning programs increasingly requires expertise in high-density power delivery, thermal management, complex rack integration and advanced supply chain coordination rather than traditional PCB assembly alone.
TrendForce expects the investment cycle to extend well beyond 2026, forecasting combined capital expenditures among the top nine CSPs to reach approximately $1.3 trillion in 2027.
The message for the EMS sector is increasingly clear: AI infrastructure demand is not only expanding, it is becoming more vertically complex, more capital intensive and more dependent on suppliers that can scale complete systems rather than individual assemblies.
Robot Orders Increase in Q2 as Automation Demand Broadens Across Industries
North American companies ordered 8,940 robots valued at $622 million in the second quarter of 2026, according to new data released by the Association for Advancing Automation (A3). Compared to the second quarter of 2025, this represents a 4.3% increase in units ordered and a 21.3% increase in revenue1. Second-quarter results brought first-half totals to 17,995 units valued at $1.166 billion, representing 2.0% growth in units and 6.6% growth in order value over the first half of 2025.
The first half of 2026 continued a trend that has been building over the past several quarters: robotics demand is becoming increasingly diversified across industries. While Automotive OEM orders declined 25% compared to the first half of 2025, growth in Automotive Component and several general industry sectors helped offset that decline, including: Semi & Electronics/Photonics: +35% units; Life Sciences/Pharma/Biomed: +32% units; Automotive Component: +24% units; Food & Consumer Goods: +17% units; Plastics & Rubber: +6% units; All Other Industries: +6% units; Metals: +3% units.
Several industries posted double-digit year-over-year gains in robot orders during the second quarter. Semi & Electronics/Photonics increased 38% year over year, while Automotive Component grew 20%. Food & Consumer Goods and Metals each increased 18%, and Life Sciences/Pharma/Biomed posted 9% growth. Non-automotive customers accounted for 56% of robot units ordered during the quarter, continuing the trend of robots being adopted across a variety of industries.
Collaborative robots continued to represent a significant portion of automation investment during the first half of 2026. Companies ordered 2,774 collaborative robots valued at $114 million, accounting for 15.4% of all robot units ordered and 9.8% of total order revenue.
“The first half of 2026 shows how the mix of the robotics market continues to evolve,” said Alex Shikany, Executive Vice President at A3. “Automotive remains an important driver of demand, while we’re also seeing growth across a wider range of industries. Results were not uniform across every sector, but the breadth of growth outside Automotive OEM is an important trend we’ll continue to watch.”
While the timing of large Automotive OEM projects and broader economic conditions will continue to influence quarterly results, the first-half data suggests manufacturers continue to view automation as a long-term investment in competitiveness.
Global OLED Monitor Shipments Grew 26.1% QoQ in 2Q26
TrendForce’s latest market research shows that the global OLED monitor market maintained strong growth momentum in 2Q26. Shipment growth was driven by the launch of new models, strong demand generated by China’s 618 shopping festival, and the continued adoption and promotion of 27-inch QHD monitors, the market’s dominant product segment.
Supported by these factors, global OLED monitor shipments increased 26.1% QoQ in 2Q26 and surged 98% YoY, nearly doubling from the same period last year. The results underscore the rapid penetration of OLED technology in the gaming and premium display markets.
Second quarter rankings of the top five OLED monitor brands remain unchanged from the previous quarter. ASUS retained the top position with a 23.1% market share, benefiting from the 618 sales event and robust demand from China’s internet café market.
Samsung’s gradual withdrawal from the Chinese market limited its ability to capitalize on seasonal demand, resulting in a significant decline in market share. Nevertheless, the company remained second with a 13.1% share. The decline also narrowed Samsung’s lead over MSI to just 0.3 percentage points, with MSI ranking third at 12.8%, supported by strong 618 promotions in China.
AOC ranked fourth with an 8.6% market share, driven by an aggressive product rollout—particularly in the 27-inch QHD segment—and steady demand in China.
LGE placed fifth with an 8.4% market share. Shipments of its 39-inch WUHD premium monitor ramped up as expected during the quarter, contributing to steady sequential growth in the brand’s OLED monitor business.
TrendForce notes that improved panel supply has enabled emerging brands to expand shipments more rapidly, narrowing the gap with the market leaders. Whether this momentum will reshape the competitive rankings remains a key trend to watch.
India Smartphone Shipments Fall 11.1% in Q2 2026 Amid Memory Chip Shortage
According to IDC’s Worldwide Quarterly Mobile Phone Tracker, India’s smartphone shipments declined 11.1% year over year to 33.2 million units in Q2 2026, as the ongoing global memory chip shortage kept component costs elevated and squeezed affordability across price bands. H1 2026 shipments fell to 64.2 million units, down 7.9% YoY, the lowest first-half volume in five years, even as market value grew 3.6% YoY. With average selling prices at record highs and vendors pulling back on discounts to protect margins, India’s price-sensitive buyers are likely to stay under pressure through the second half of the year.
Q2 2026 confirms this downturn isn’t spread evenly across the market. The memory cost surge is rewarding brands with scale and premium portfolios while hitting those anchored to low-end volume hardest.
Apple: Shipments held largely flat, constrained by supply shortages on the iPhone 15, 16, and 17. Despite the shortage, the iPhone 17 remained the top-shipped device consecutively for Q1/Q2’26. Consumer demand remained strong at its core, though it cooled somewhat as affordability offers grew scarce.
Samsung: Shipments stayed largely flat, placing it alongside Apple as one of the few brands that maintained ground in a shrinking market. A diversified portfolio and greater scale allowed Samsung to absorb rising costs without sacrificing volume or margins.
Chinese brands: Faced the sharpest exposure, as their traditional strength in the low-end and mass-budget segments worked against them. Cost cutting and portfolio shifts toward higher-margin models were underway, but the harder challenge was convincing price-sensitive buyers raised on budget positioning to accept meaningfully higher price tags. With financing options narrowing the price gap between segments, several leading Chinese manufacturers saw sharper, double-digit declines as demand tilted toward brands with stronger scale and supply chain stability.
High-Frequency High-Speed CCL Market to Reach $3.1B by 2035
The global high frequency high speed copper clad laminate market was valued at $4.5 billion in 2025 and is estimated to grow at a CAGR of 10.3% to reach $11.8 billion by 2035.
Market growth is supported by the accelerated development of 5G communication infrastructure, increasing investments in artificial intelligence (AI) servers and high-performance computing (HPC) systems, rising integration of advanced driver assistance systems (ADAS) and autonomous vehicle electronics, expanding high-speed data requirements from cloud platforms and hyperscale data centers, and ongoing electronic device miniaturization. The increasing complexity of modern electronic systems is creating stronger demand for copper clad laminates (CCLs) that provide low signal loss, high thermal stability, and reliable performance in advanced printed circuit board (PCB) applications.
The transition toward faster communication networks and next-generation computing environments is encouraging manufacturers to develop materials capable of supporting higher frequencies and improved signal integrity. Growing adoption of advanced electronic architectures across the telecommunications, automotive, data processing, and consumer electronics sectors continues to strengthen the long-term outlook for high frequency high speed copper clad laminates.
The high-speed CCL segment accounted for a 67.6% share in 2025. This segment maintains strong demand due to its widespread use in advanced applications such as AI servers, cloud computing infrastructure, hyperscale data centers, HPC platforms, enterprise networking systems, and high-speed switching equipment. Increasing adoption of high-speed data transmission technologies, including 112 Gbps, 224 Gbps, and future-generation communication standards, is driving demand for ultra-low-loss laminate materials that improve signal integrity and reduce insertion loss. Continued investment in AI infrastructure and data center expansion is further supporting segment growth.
The multilayer core laminates segment reached USD 3.1 billion in 2025. Growth in this segment is supported by increasing utilization across AI servers, HPC systems, cloud data centers, telecommunications equipment, high-speed switches, and advanced automotive electronic systems. Multilayer core laminates provide enhanced routing density, improved signal integrity, strong thermal performance, and the ability to support complex multilayer PCB structures. Their capability to manage high-speed differential signaling while reducing transmission loss enables a wide range of advanced electronic devices to achieve faster connectivity and improved operational reliability.
The North American high frequency high speed copper clad laminate market accounted for a 23.6% share in 2025, driven by rising AI infrastructure investments, expanding hyperscale data center capacity, advancements in semiconductor technologies, and continued deployment of 5G communication networks. The region is home to major cloud service providers, semiconductor companies, and communication equipment manufacturers that require advanced CCL materials with high-speed and low-loss characteristics. High-performance PCB materials are becoming increasingly important for supporting AI servers, ultra-fast switching systems, advanced computing platforms, and next-generation electronic technologies.
Prominent players operating in the global high frequency high speed copper clad laminate industry include Rogers Corporation, Panasonic Industry Co., Ltd., AGC Inc. (AGC Multi-Material), Isola Group, Mitsubishi Gas Chemical Company, Inc. (MGC), Elite Material Co., Ltd. (EMC), Doosan Corporation Electro-Materials, Shengyi Technology Co., Ltd. (SYTECH), Taiwan Union Technology Corporation (TUC), Nan Ya Plastics Corporation, Resonac Holdings Corporation, Chukoh Chemical Industries, Ltd., ITEQ Corporation, and Ventec International Group.
© 2026 IPC International Inc. DBA Global Electronics Association